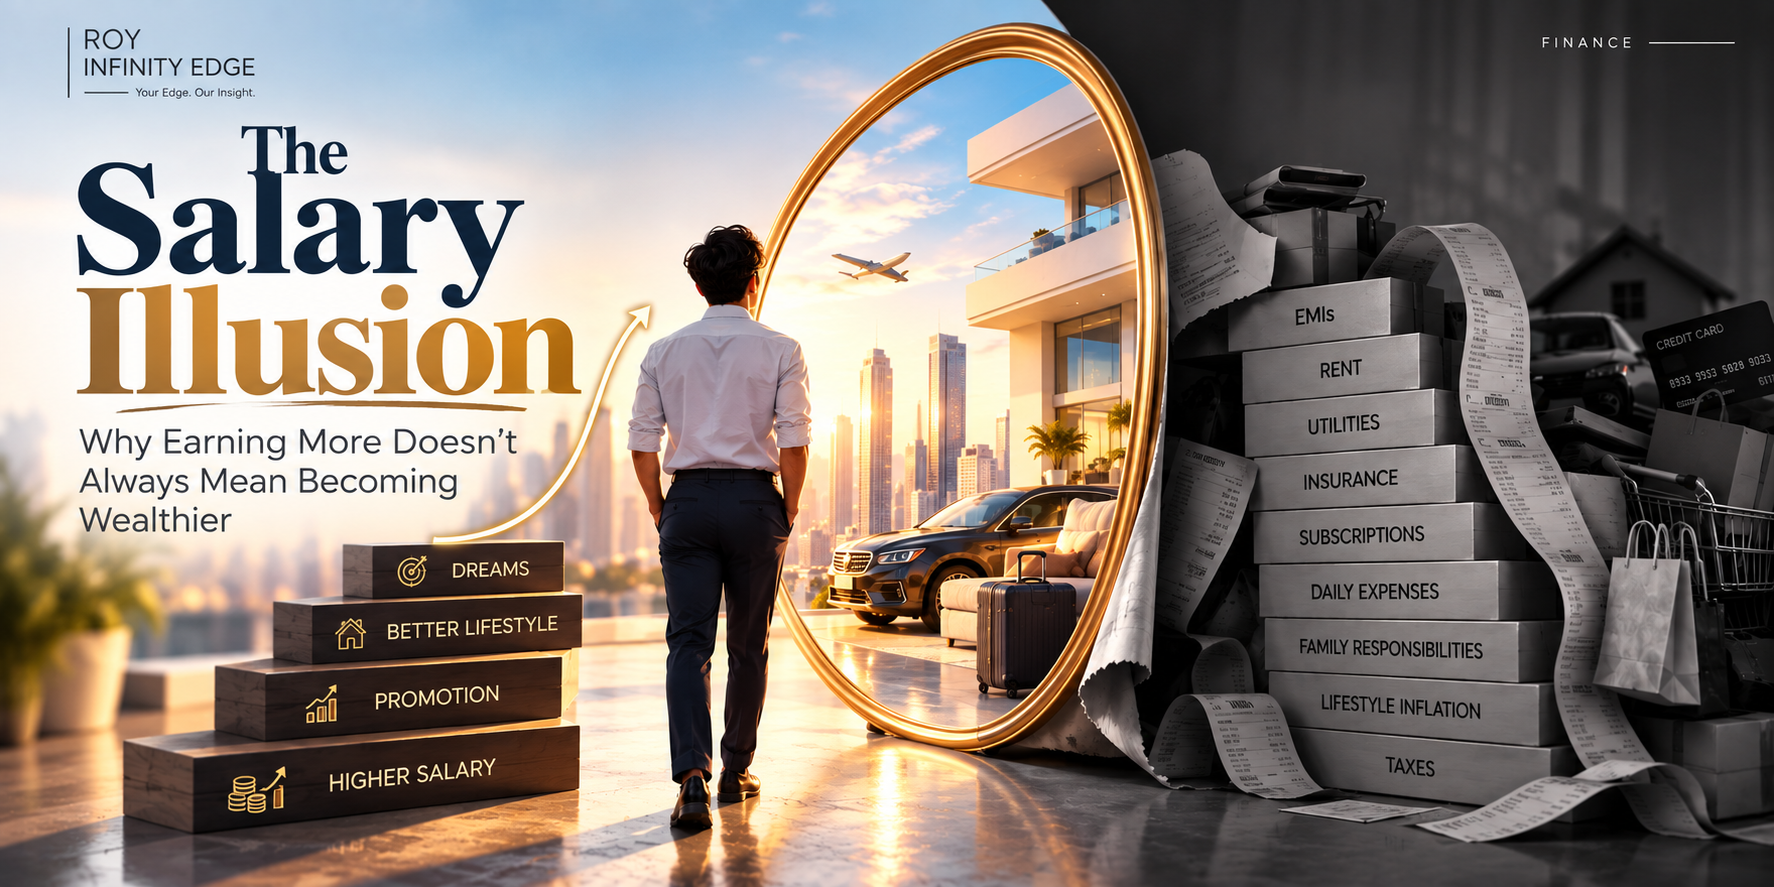
A salary increase is usually treated as unmistakable good news.
The number on the payslip goes up. The designation may improve. The bank balance may look healthier. Perhaps a larger apartment becomes affordable, a newer car seems reasonable, better restaurants become routine and purchases that once required consideration become ordinary.
From the outside, it looks like financial progress.
But there is a question that rarely gets asked when income increases:
How much richer did the person actually become?
This question exposes what can be called the Salary Illusion—the tendency to confuse a higher income with greater financial strength.
A person can earn significantly more than they did five years ago and still feel financially constrained. Their salary has increased, but so have their commitments, expectations and monthly obligations.
The income is larger.
The financial freedom is not necessarily larger.
The Payslip Can Grow Faster Than Financial Security
Income is one of the most visible measures of financial progress because it is easy to compare.
Someone earning ₹30,000 a month and later earning ₹60,000 appears to have made substantial progress. Mathematically, their income has doubled.
But income is only the beginning of the financial picture.
What matters is what happens to that additional income after housing, transportation, education, subscriptions, EMIs, insurance, lifestyle spending, family responsibilities and other recurring commitments are accounted for.
If most of the additional income is immediately absorbed by additional spending, the person's financial capacity may have changed far less than the salary suggests.
This is where the illusion begins.
The Quiet Mathematics of Lifestyle Inflation
Lifestyle inflation rarely arrives as one dramatic financial decision.
It usually arrives in small, reasonable-looking upgrades.
- A slightly better apartment.
- A more expensive vehicle.
- More frequent food delivery.
- A premium smartphone.
- More subscriptions.
- More frequent travel.
- Higher expectations around social occasions.
- Convenience services that gradually become necessities.
None of these decisions is automatically irresponsible.
The problem occurs when every increase in income automatically creates a corresponding increase in the cost of maintaining one's lifestyle.
Eventually, the higher salary stops feeling like additional capacity and starts feeling like the minimum amount required to maintain the new normal.
That is the paradox.
The lifestyle that once represented financial progress can eventually become the reason financial progress feels invisible.
When “I Can Afford It” Becomes a Dangerous Financial Test
One of the most misleading questions in personal finance is:
“Can I afford this?”
If the answer is based only on whether the monthly payment fits inside the current salary, the calculation is incomplete.
A purchase can be affordable in the narrow sense and still reduce financial flexibility.
Consider two people with identical incomes.
The first has a substantial portion of income committed to EMIs and recurring expenses. The second has fewer fixed obligations and regularly retains a meaningful portion of income.
On paper, they earn the same.
Financially, they are not in the same position.
The second person has something increasingly valuable: room to manoeuvre.
That room can absorb an unexpected expense, support a career change, fund an opportunity or simply reduce dependence on the next month's salary.
The Difference Between Income and Financial Capacity
Income tells us how much money enters a person's financial system.
It does not tell us how much flexibility that system possesses.
A more useful way to think about personal financial strength is through several layers:
- Income: What comes in.
- Expenses: What goes out.
- Fixed commitments: What must go out regularly.
- Retained cash: What remains available.
- Assets: What can contribute to future financial strength.
- Debt: What future income has already been committed to.
- Financial resilience: How well the person can withstand disruption.
This distinction matters because two people with identical salaries can have completely different financial realities.
The Real Cost of a Higher Lifestyle
A higher lifestyle has an important characteristic that is easy to overlook: many of its costs are recurring.
A one-time purchase is one thing. A permanently higher monthly expense is another.
When a person upgrades their lifestyle, they may not simply spend more this month. They may create a new baseline for every month that follows.
That baseline can include rent, vehicle payments, maintenance, insurance, memberships, subscriptions, domestic services, dining habits and social expectations.
This is why lifestyle inflation can be more consequential than occasional impulse spending.
The issue is not necessarily the size of an individual purchase. It is the creation of a financial structure that becomes increasingly expensive to maintain.
Why Promotions Can Create a Financial Trap
Career progression often creates the strongest version of the Salary Illusion.
A promotion brings higher income and often a stronger professional identity. With it can come a subtle psychological shift:
“I have moved up, so my lifestyle should move up too.”
There is nothing inherently wrong with enjoying the rewards of professional growth.
But if every promotion is immediately converted into a more expensive lifestyle, future salary increases become increasingly necessary just to preserve the current standard of living.
The result can be a strange situation in which someone is objectively earning well but subjectively feels that they cannot slow down.
They are earning more, yet becoming increasingly dependent on continuing to earn more.
The Invisible Pressure of Social Comparison
Salary decisions do not happen in isolation.
People observe colleagues, friends, relatives and social media. They see new cars, holidays, homes, restaurants, gadgets and professional lifestyles.
The comparison is particularly dangerous because people generally see consumption more easily than financial structure.
You can see someone's car.
You cannot see their outstanding loan.
You can see the holiday.
You cannot see whether it was funded from savings, income or debt.
You can see someone's lifestyle.
You cannot see their emergency reserve, investments or financial obligations.
Comparing visible consumption with invisible financial health is therefore an unreliable exercise.
The Salary Test Is Not the Wealth Test
Salary is a measure of earning power.
Wealth is a broader measure of accumulated financial resources and ownership.
The distinction is important.
A high-income individual can have substantial financial obligations and limited accumulated assets. Another person with a lower income may have fewer liabilities, meaningful savings and steadily growing assets.
Neither situation should be judged solely from the monthly salary.
The more useful question is not:
“How much do you earn?”
It is:
“What is your income allowing you to build?”
Financial Progress Should Leave Evidence
Genuine financial progress should become visible somewhere in a person's financial structure.
It might appear as:
- A stronger emergency reserve.
- Lower dependence on consumer debt.
- Increasing investments or other productive assets.
- Greater ability to handle unexpected expenses.
- More freedom to make career decisions.
- Reduced financial dependence on the next salary.
- A growing gap between income and necessary expenditure.
The exact form will differ from person to person.
But if income has risen substantially over several years and none of these forms of financial capacity has meaningfully improved, it is worth asking where the additional income has gone.
The Most Valuable Part of a Raise May Be the Part You Never Spend
This is where a salary increase can become genuinely powerful.
The first instinct after receiving a raise is often to ask what the additional money can buy.
A better financial question is:
What portion of this increase can permanently improve my future financial position?
That portion can strengthen savings, investments, debt reduction or financial reserves.
The remaining income can still improve present-day quality of life.
This does not require rejecting comfort or living permanently below one's means. It requires separating lifestyle improvement from financial progress.
Not Every Expense Increase Is Bad
The Salary Illusion should not be interpreted as an argument against spending more as income increases.
That would be an equally simplistic conclusion.
Higher income can legitimately support better housing, better nutrition, education, healthcare, travel, family support, convenience and experiences.
Quality of life matters.
The issue is whether higher spending is intentional or automatic.
There is a significant difference between saying, “I choose to spend more because this matters to me,” and discovering that spending has increased simply because income increased.
The first is a choice.
The second can become a pattern.
A Raise Should Increase Options, Not Just Expenses
The strongest financial benefit of increasing income is not necessarily the ability to buy more.
It is the ability to have more choices.
More financial capacity can mean the ability to leave an unsuitable job, take time to retrain, support a family member, withstand an unexpected expense, pursue an opportunity or simply say no to something without immediate financial consequences.
That is a deeper form of wealth.
Money becomes valuable not only because of what it can purchase, but because of the choices it makes possible.
The Financial Freedom Gap
Imagine two employees receiving identical salary increases.
Employee A uses the additional income to upgrade nearly every aspect of their lifestyle. Within a year, the higher salary has become the foundation of a more expensive monthly routine.
Employee B improves some aspects of life but deliberately retains part of the increase as savings, investments or debt reduction.
After several years, their salaries may look similar, but their financial positions can be very different.
Employee A may need the higher income simply to maintain the lifestyle they have built.
Employee B may have accumulated something that does not appear on the payslip: financial optionality.
That difference is easy to miss because financial optionality is not visible.
It does not arrive with a new car or a larger house.
It appears when circumstances change and one person has choices while the other has obligations.
The Salary Illusion Is Psychological as Much as Financial
There is a deeper reason this phenomenon persists.
People tend to adapt to improvements in living standards remarkably quickly.
What once felt like a luxury can eventually feel ordinary. What once seemed unnecessary can become part of the expected lifestyle.
This creates a moving target.
The salary increases, the lifestyle increases, expectations increase, and the emotional experience of financial progress gradually disappears.
The person may therefore continue pursuing higher income without asking whether the additional income is actually producing greater freedom.
That is why the Salary Illusion is not merely a budgeting problem.
It is also a problem of perception.
What Should Happen When Income Rises?
There is no universal percentage that every person should save or invest after receiving a raise. Financial circumstances differ.
But one principle is broadly useful:
Do not allow every increase in income to become a permanent increase in your cost of living.
A salary increase can serve several purposes at once.
- Improve current quality of life.
- Strengthen financial reserves.
- Reduce expensive debt.
- Increase long-term investments.
- Create greater financial flexibility.
The objective is not to reject consumption.
It is to ensure that some part of increased earning power becomes increased financial strength.
The Better Question to Ask After a Raise
The next time your income increases, there is an obvious question to ask:
“What can I afford now?”
But there is a better one.
“What can I build now that I could not build before?”
The first question focuses on consumption.
The second focuses on capacity.
That distinction can change the way a person thinks about salary growth.
When More Income Actually Becomes More Wealth
A higher salary is valuable. It expands possibilities and can significantly improve a person's financial life.
But higher income becomes meaningful financial progress only when some of that additional earning power survives beyond the immediate upgrade in lifestyle.
It needs somewhere to go.
Into resilience.
Into assets.
Into lower liabilities.
Into greater flexibility.
Into choices that future income cannot guarantee.
That is the difference between earning more and becoming financially stronger.
Beyond the Payslip
The Salary Illusion is ultimately not an argument against ambition, higher salaries or a better lifestyle.
It is an argument against using income as the only evidence of financial progress.
A larger salary can improve your life. But if every increase is immediately converted into a larger set of obligations, the financial benefit may be far smaller than the payslip suggests.
True financial progress should gradually create something money can buy but consumption cannot easily show: freedom of choice.
So the next time your salary rises, celebrate it.
Enjoy some of it.
Improve your life if you genuinely value the improvement.
But also ask the question that the Salary Illusion encourages us to ask:
“After earning more, what have I actually become financially capable of doing that I could not do before?”
Because a bigger salary is an increase in income.
It becomes an increase in wealth only when it changes your financial position—not merely your spending.